
NFI Group revenue, earnings up
Trending
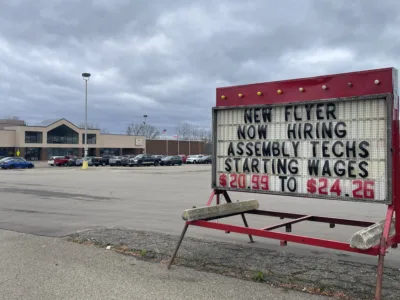
Revenues and earnings are up at NFI Group, owner of the New Flyer manufacturing plant on Fluvanna Avenue in Jamestown, both for the third quarter of 2026 and for the year to date compared to 2025.
NFI posted third quarter revenues of $1,007,400 in the third quarter, up 23.1% from the $879,000 in the third quarter of 2025. For the year, the company has posted revenue of $3,904,000, an increase from the $3,426,500 posted in the first nine months of 2025. Net earnings in the third quarter of 2026 were $100,000, compared to a loss of $140.9 million in the third quarter of 2025 due to costs associated with a battery recall. Net earnings year to date at $195 million through the end of September 2026 compared to a loss of $2,433,400 through the first three quarters of 2025. Deliveries company wide are essentially the same in the third quarter of both years, with production increasing slightly year-to-date.
John Sapp, NFI Group president and CEO, said 2026 has been a strong year through the first three quarters in part because of past operational changes that took effect in the second quarter and paid off even more in the third quarter. Past conference calls with investor analysts have focused as much on supply chain issues that were a drag on the company's bottom line as they did with sales numbers. Those issues were a less prevalent discussion on the most recent conference call, and Sapp said that is reflected in the company's bottom line.
"Frankly, what you’re seeing in the results is exactly that. (The third quarter) was a really strong quarter for us, and it was really driven by the improvement that we’ve seen in linearity and driven heavily from our North America Transit and the coach business. What that has done for us, of course, is allowed from a delivery standpoint where we have historically relied heavily on a (the fourth quarter), right, to be able to have those deliveries in place, not stack up into the back half of the year, but instead deliver that linearity and achieve a much higher degree of efficiency as a result. ... We’re anticipating very strong production, especially within our North America Transit as well as the Coach space that we historically see in (the fourth quarter). The guidance range that we have or that we’re sharing here, we’re bringing up the bottom half of that, I think is reflective of us anticipating continued linearity in terms of what we’ve done from a production standpoint. (The fourth quarter) we still anticipate to be one of our strongest quarters. At the same time, it’s reflective of some important operational changes that we’ve done in the business to drive the linearity and get off the dependence of a constant strong end-of-year finish."
Manufacturing revenue of $836.7 million increased by 15.8% from the third quarter in 2025, which company officials said reflects higher deliveries in North American transit and motorcoach markets, though there was a decrease in deliveries in the medium-duty and cutaway segment and international transit markets. Manufacturing net earnings of $9.1 million, an increase of $141 million from the third quarter of 2025, was driven by higher revenues and improved gross margins as well as the 2025 third quarter financial hit seen by the battery recall.
NFI received orders for 4,409 EUs for the first nine months in 2026, with company officials expecting continued order success for the remainder of 2026 and into 2027 reflecting strong customer demand in NFI's transit,
motorcoach, and medium-duty markets. The company reports active bids on 7,793 units and a five-year projected customer demand of 23,449 units, a 2.1% increase from the same period in 2025.
Company officials also see increased use of public transit systems according to the most recent American Public Transportation Association Ridership Trends Dashboard report showing 2026 second quarter bus ridership increasing 3.2% from the same 12-month period in 2025. APTA also reports that the average fleet age is at 8.2 years, and the Canadian Urban Transit Association reports the average age at 10.4 years.
NFI expects increased vehicle deliveries from North American transit backlog conversion and higher motorcoach volumes. These higher deliveries are expected to improve overhead and fixed cost absorption within the manufacturing segment.
"Our performance through the first three quarters gives us additional confidence in our 2026 guidance. As a result, we have raised the lower end of our Adjusted EBITDA guidance by $10 million, now implying a year-over-year improvement of 18% to 24%. This progress demonstrates the strength of NFI's business and our operating momentum," Sapp said.